The Insurance Affordability Crunch: Navigating the New Normal of Rising Premiums
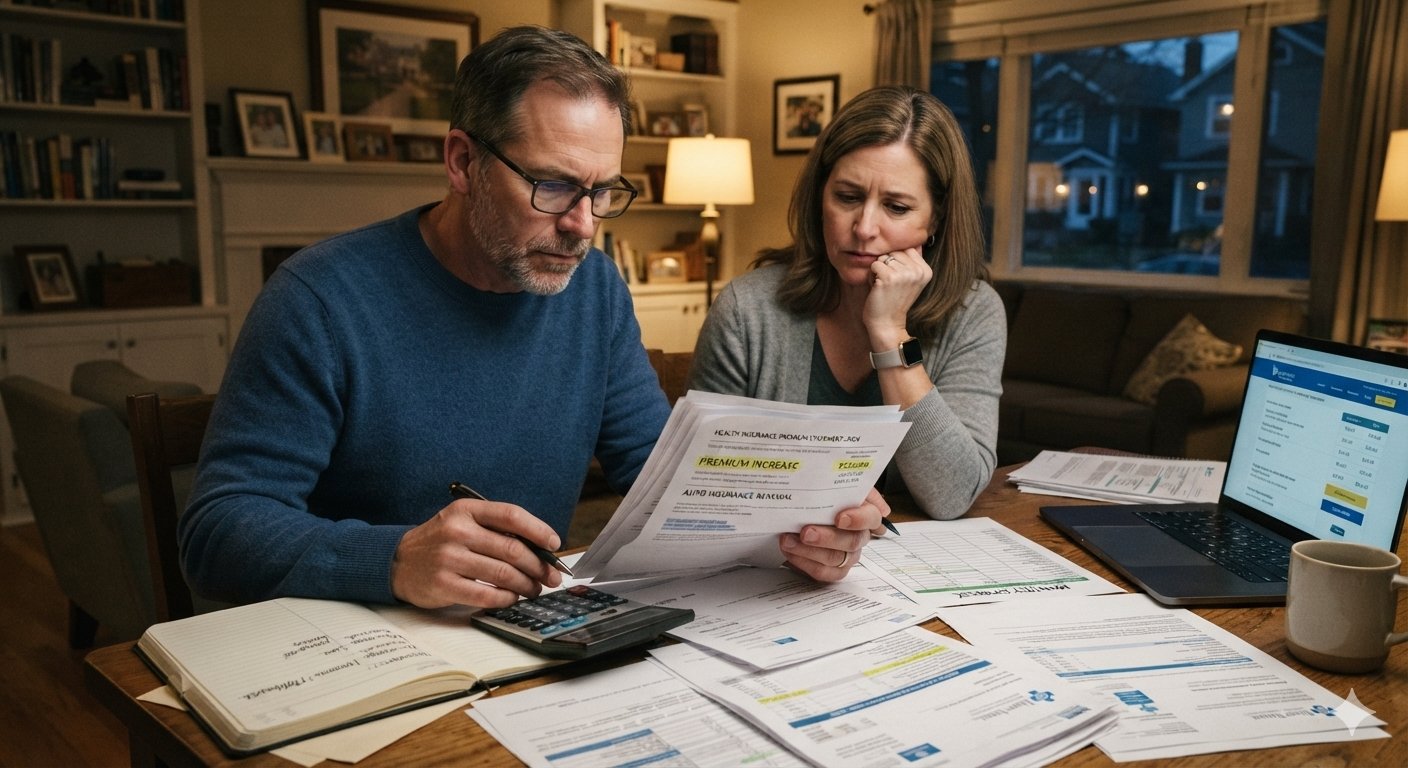
Across households and boardrooms alike, a singular financial pressure point has taken center stage: insurance affordability. Whether it is auto, home, or health coverage, soaring premiums are stretching household budgets to their absolute limits.
What was once viewed as a routine fixed expense has transformed into a major financial challenge. Understanding the forces driving this crisis—and learning how to navigate them—is more crucial than ever for maintaining long-term financial security.
1. What is Driving the Affordability Crisis?
The spike in insurance costs isn’t happening in a vacuum. Insurers across sectors are grappling with a convergence of compounding pressures:
- Extreme Weather and Climate Risks:The increasing frequency and severity of natural disasters—such as wildfires, hurricanes, and severe storms—have driven property and casualty losses to historic highs, forcing insurers to hike rates or pull back from high-risk regions altogether.
- Escalating Replacement and Repair Costs: Inflation, supply chain bottlenecks, and rising labor costs mean that fixing a wrecked vehicle, rebuilding a storm-damaged roof, or paying out medical claims cost significantly more than they did just a few years ago.
- Social Inflation and Litigation:In the casualty and liability spaces, increasing litigation expenses and higher jury awards (“social inflation”) have inflated the cost of settling claims, costs that ultimately trickle down to everyday policyholders.
- Healthcare Inflation:For health insurance, medical care costs continue to outpace general inflation due to advanced technologies, an aging population, and intensive service utilization.
2. The Ripple Effects on Households
When insurance costs outpace wage growth, the consequences go far beyond a heavier monthly bill.
- The Underinsurance Trap: To keep monthly premiums manageable, many consumers are opting for higher deductibles or stripping away vital coverages. This leaves them dangerously exposed to catastrophic out-of-pocket expenses if an accident or disaster strikes.
- Forced Decisions and Availability Gaps: In some regions, certain types of property insurance are becoming nearly impossible to find. Homeowners find themselves priced out of their communities or forced to rely on expensive state-backed “insurer of last resort” pools.
- Erosion of Trust: As bills climb, policyholders are demanding more transparency. Studies show that customer satisfaction plummets when policy terms are confusing or when insurers fail to proactively communicate why rates are changing.
3. Practical Strategies to Protect Your Budget
While systemic solutions like regulatory reform and risk mitigation will take time, you can take immediate steps to manage your insurance expenses without leaving yourself unprotected:
- Re-shop Your Policies Annually: Loyalty doesn’t always pay in the insurance market. Compare rates from at least three different carriers to ensure you are getting a competitive price.
- Optimize Deductibles: If you have an emergency fund capable of covering a higher unexpected expense, raising your auto or home insurance deductible can significantly lower your monthly premium.
- Bundle and Audit Discounts: Consolidating your home and auto policies with a single provider often unlocks substantial multi-policy discounts. Additionally, ask your provider about safe-driver trackers, home security upgrades, or paperless billing discounts.
- Review Coverage Limits: Periodically assess whether your coverage matches your actual current needs. For instance, ensure your life or property insurance limits reflect realistic modern replacement values rather than outdated figures.
Looking Ahead
The insurance affordability crunch underscores a fundamental economic reality: risk management is getting more expensive. While insurers lean heavily into artificial intelligence, advanced data analytics, and granular risk-assessing models to stabilize pricing, consumers must remain proactive. By staying informed, re-evaluating policies regularly, and communicating closely with providers, you can strike the right balance between comprehensive protection and financial sustainability.
How are rising insurance costs impacting your household budgeting strategy this year?